


MultiChoice Is Rewriting the Pay-TV Playbook. But Can the New Packages Bring Viewers Back?
The broadcaster’s latest package overhaul signals a bigger shift in how television is priced, distributed and consumed across Africa.
The television industry is undergoing a fundamental change, and MultiChoice’s latest decision to restructure its DStv packages across African markets offers an interesting indication of where the business is heading.
For years, pay-TV operators built their business around a tiered subscription model. Customers paid more to access more channels, with premium sports, international productions and exclusive entertainment largely reserved for the most expensive packages.
That model is now being challenged. On-demand streaming, changing household spending patterns, internet-based entertainment and widespread content piracy have fundamentally altered how audiences think about television subscriptions. Consumers are no longer necessarily interested in paying for hundreds of channels. Increasingly, they want access to the particular content they enjoy, at a price they consider reasonable.
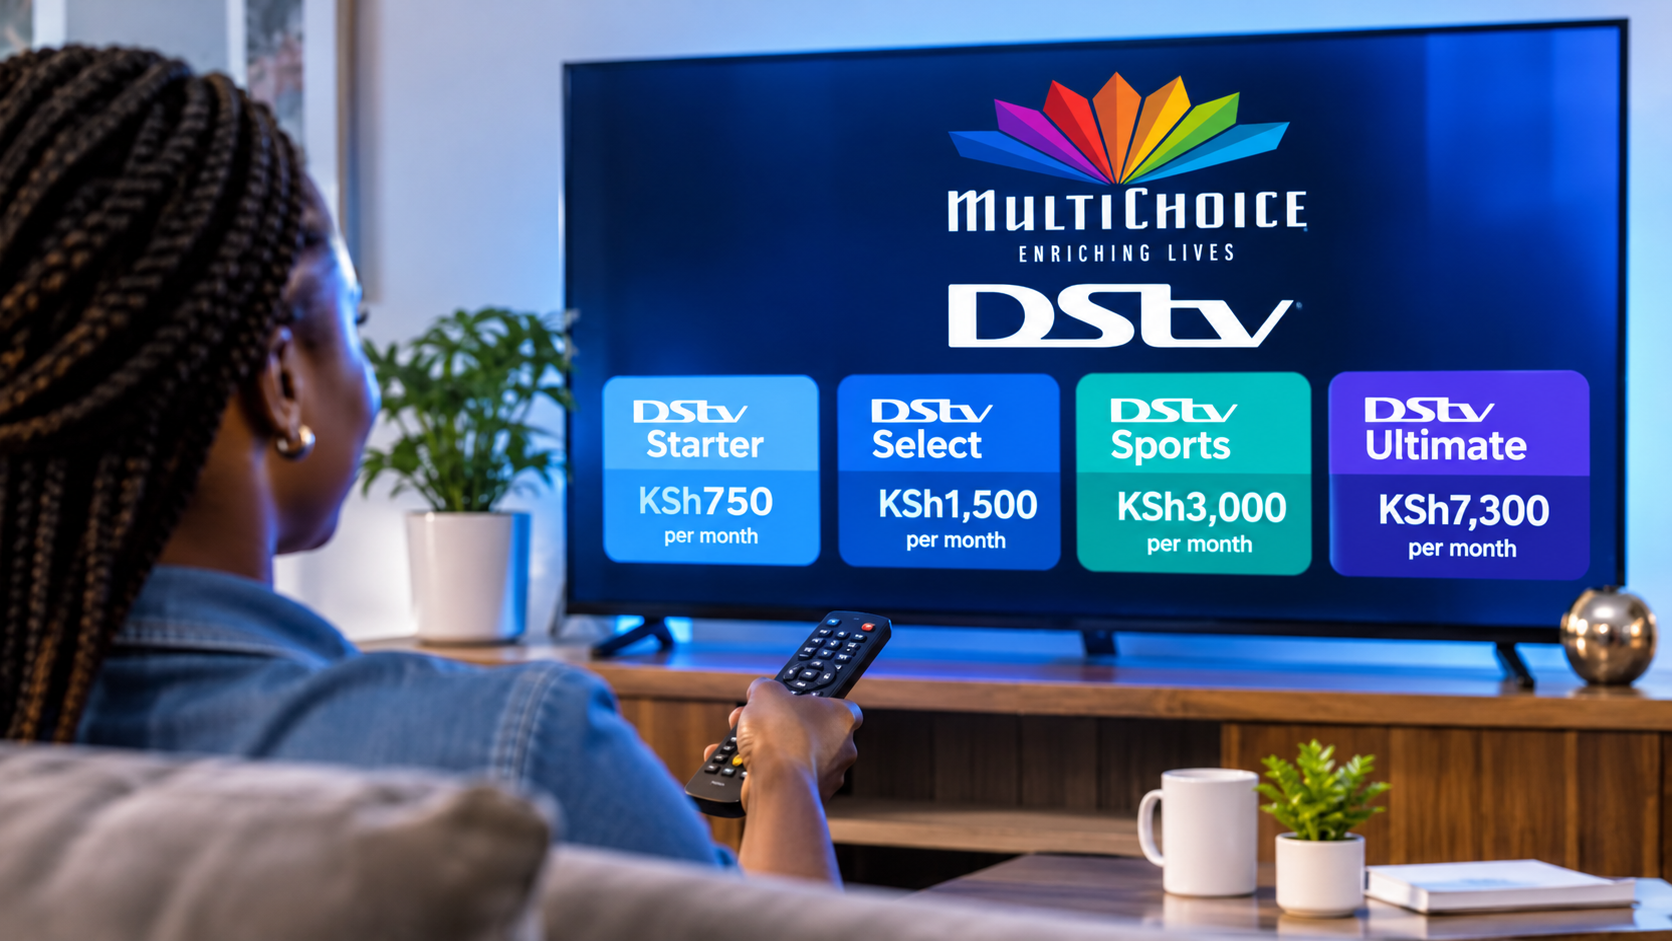
MultiChoice appears to be responding to that reality. From November 5, 2026, the company, now operating under CANAL+ ownership, introduced a redesigned DStv package structure across several sub-Saharan African markets. The changes replace the previous six-bouquet structure in markets such as Kenya with four principal offerings: Starter, Select, Sports and Ultimate.
The significance, however, extends beyond a change in package names. It represents a rethink of the commercial model that has supported traditional pay-TV for decades.
The economics of keeping subscribers
Perhaps the clearest indication of why this restructuring matters can be found in MultiChoice’s subscriber numbers.
In Kenya, the company’s position has come under considerable pressure. According to the Communications Authority of Kenya, active DStv subscriptions declined from 270,503 in December 2025 to 248,053 in March 2026, an 8.3 per cent quarterly drop. These figures tell an important story about the pressure facing traditional pay-TV operators.
For a long time, the business could rely on a relatively predictable relationship between subscription prices and revenue. Customers who wanted access to premium content had to move up the bouquet ladder. But that relationship becomes difficult to sustain when consumers begin questioning whether the additional channels justify the additional cost.
MultiChoice’s response is particularly visible in the Kenyan market, where DStv Ultimate has dropped from KSh11,700 to KSh7,300 per month, representing a 37.6 per cent reduction. The new DStv Starter costs KSh750, Select KSh1,500 and Sports KSh3,000.
This is a significant adjustment, particularly at the premium end of the market. It suggests that the company is increasingly prioritising subscriber retention and market reach over maintaining high subscription prices at all costs.
There is a commercial trade-off here. Lower prices can attract more households, but the company must generate sufficient subscriber growth to compensate for the reduced revenue per customer.
In other words, the challenge is no longer simply how much each subscriber pays. It is how many subscribers the business can retain and attract while keeping the economics sustainable.
Television is becoming more about choice than channels
Another interesting aspect of the restructuring is how the new packages are organised.
The introduction of a dedicated DStv Sports package is particularly significant. Rather than making audiences subscribe to an expensive premium bouquet to access major sporting competitions, MultiChoice is bringing more of that content into a separate sports-focused offering.
In Kenya, the KSh3,000 package includes all English Premier League and UEFA Champions League matches, alongside other sporting competitions and entertainment channels.
This is a notable shift in how premium content is distributed.
It recognises that audiences do not necessarily consume television in the same way. A household interested primarily in football may have very different subscription priorities from one that watches local drama, children’s programming, movies and international series.
The industry is gradually moving towards a more segmented approach, where content preferences become central to subscription decisions. There is also a potential opportunity for broadcasters and advertisers. Better-defined audience segments could make it easier to understand viewing preferences and develop more targeted commercial propositions.
However, the real test will be whether subscribers perceive these packages as genuinely better value, rather than simply a different arrangement of existing channels.
Streaming has changed the competition
It would be difficult to understand MultiChoice’s decision without considering the broader streaming market. Platforms such as Netflix, YouTube and other digital entertainment services have fundamentally changed audience expectations.
Viewers are increasingly accustomed to choosing what they want to watch, when they want to watch it, and on which device. This has challenged the traditional pay-TV model, which has historically relied on scheduled programming, fixed monthly subscriptions and bundles containing channels that individual households may rarely watch.
The competition is also no longer limited to licensed streaming platforms. Free online video, social media and illegal streaming services have created additional alternatives for consumers. For MultiChoice, this means that lowering subscription prices is only one part of the solution. The company must also demonstrate why a traditional television subscription remains relevant in a world where entertainment is increasingly accessible through the internet.
Live sports remains one of its strongest advantages. Unlike films and series, major sporting events are time-sensitive. Fans want to watch matches as they happen, making reliable access to live competitions a compelling reason to maintain a subscription. The challenge will be translating that advantage into a product that is affordable, convenient and accessible across different devices.
The CANAL+ factor: A different approach to African television
The restructuring also needs to be viewed in the context of CANAL+’s acquisition of MultiChoice.
The French media group’s involvement introduces a different strategic perspective on how the broadcaster can operate across markets, distribute content and build its subscriber base.
Interestingly, the new package structures are not identical everywhere. South Africa has a five-package structure, including a separate Movies and Series offering, while several other sub-Saharan African markets, including Kenya, have adopted four packages.
This suggests that the business is pursuing a common strategic direction while retaining room for market-specific decisions.
There is a bigger opportunity here: CANAL+ can potentially leverage its international content relationships, distribution infrastructure and experience in different African markets to strengthen MultiChoice’s position.
But scale alone will not guarantee success. African markets have different income levels, viewing preferences, internet infrastructure and competitive pressures. A pricing strategy that works in South Africa may not necessarily translate to Kenya, Ghana, Uganda or Nigeria.
The ability to localise the offering will therefore be just as important as the decision to simplify it.
Local content could become an even bigger differentiator
One area that deserves greater attention in this transition is African content.
As international streaming platforms expand their presence across the continent, local storytelling presents an opportunity for traditional broadcasters to differentiate themselves.
MultiChoice has spent years developing local productions through platforms such as Maisha Magic, and making some of this programming available at lower subscription levels could help strengthen its appeal beyond premium sports audiences.
For instance, placing Kenyan productions such as Chamaa on the entry-level DStv Starter package potentially expands their reach to households that might previously have been priced out of accessing them.
This is important for two reasons.
First, local content creates a stronger connection with audiences because it reflects their languages, cultures and everyday experiences.
Second, it supports the wider creative economy, including production companies, actors, writers, directors and other industry professionals.
Mass Exits in Africa: A Crisis or a Catalyst for Reinvention?
The future of African pay-TV will therefore not be determined by international sports rights alone. The ability to consistently produce compelling local programming could become an equally important competitive advantage.
So, what does the future of pay-TV look like?
The bigger question is whether this restructuring represents a temporary attempt to recover lost subscribers or the beginning of a more permanent transformation of the industry.
We believe it is likely to be the latter.
Traditional pay-TV will increasingly have to operate as part of a broader entertainment ecosystem rather than as a standalone television service.
That ecosystem will likely be built around several developments.
-
More flexible subscriptions: Consumers will increasingly expect packages that reflect their viewing habits, with less pressure to pay for content they do not consume.
-
Stronger digital integration: Satellite television and streaming will need to work together, allowing subscribers to move between the television screen, smartphones and other connected devices.
-
More competitive pricing: Subscription affordability will become central to customer acquisition and retention, particularly in markets where household purchasing power remains constrained.
-
Greater investment in local content: African productions will be essential in attracting and retaining audiences while creating opportunities for the continent’s creative industries.
-
New approaches to sports distribution: Live sports will remain valuable, but broadcasters may need to explore more flexible ways of making sporting content accessible.
There is, however, one important consideration: cheaper packages do not automatically translate into a sustainable business.
MultiChoice must balance affordability with the rising costs of acquiring premium sports rights, producing original content, maintaining distribution infrastructure and investing in technology.
It must also address piracy, which continues to undermine the commercial value of premium content.
The question is whether a larger, more affordable subscriber base can generate enough revenue to support these investments.
That is where the real test of the new strategy lies.
A new chapter for African television
For MultiChoice, the latest package changes represent an acknowledgement that the old way of selling television may no longer be sufficient.
The company is moving from a model that largely rewarded customers willing to pay for premium bundles towards one that places greater emphasis on affordability, choice and wider content accessibility.
It is a necessary adjustment in an increasingly competitive entertainment market.
But perhaps the most important lesson for the wider industry is that television is no longer competing only with other television providers. It is competing for consumers’ time, attention and disposable income.
The platforms that understand this will be better positioned to remain relevant. Pay-TV is unlikely to disappear. However, its future may look very different from the subscription model that defined the industry for decades.
The next phase will not necessarily belong to the broadcaster with the most channels or the most expensive bouquet. It may belong to the one that understands its audience well enough to give people the content they want, at a price they are willing to pay, and on a platform they can access conveniently.
